

Too Much Unfamiliar Information? You Need a Starting Point, Not the Whole Picture
You know what you want to understand, but every explanation introduces five more unfamiliar terms. To focus on making a difficult subject manageable, find its essential parts, choose one small question and practice answering it before adding another. With compound interest, your starting point can be a single interest calculation.
The problem is often the number of things arriving together. A guide might mention principal, interest rates, compounding frequency, annual returns and a formula before you have worked out what happens to your first $100. Each detail has a place, but you do not need to hold them all in mind at once. You need a sequence in which each new idea has something familiar to attach to.
Replace “understand compound interest” with a narrower first question: “How much interest would $100 earn over one year at a fixed rate?” That question has a clear finish line. You can identify the starting amount, calculate the interest and check the result. The wider subject has not disappeared; you have simply given yourself a usable entrance. Keep other questions on a separate note so that noticing them does not mean you must answer them immediately.
Identify the Essentials: What You Need to Understand Compound Interest
Start by deciding what you want to be able to explain. For compound interest, a useful first goal is: “I can show how a balance grows when previously earned interest stays in the account and also earns interest.” This is more specific than knowing every term associated with saving or borrowing. It also tells you which details belong at the beginning.
You need four essentials: the starting amount, the interest rate, the period that rate applies to and what happens to the interest afterward. The starting amount is often called the principal. For a deliberately simple example, suppose you begin with $100, earn a fixed annual rate of , and have interest added once a year. Assume there are no deposits, withdrawals, fees or taxes. These assumptions keep the example focused; they are not a promise about any real account.
After the first year, the account earns $5 and holds $105. The important next question is whether the following year's interest is calculated on the original $100 or the new $105. That distinction is the heart of compounding. Monthly calculations, changing rates and inflation can wait until you can explain this basic mechanism.
Break the Essentials Into Small Topics You Can Practise One at a Time
A topic is small enough when it asks you to do one identifiable thing and gives you a result you can check. “Interest rates” is still broad. “Find five per cent of $100” is manageable. So is “add the interest to the starting balance.” These tasks belong together eventually, but separating them shows you exactly where uncertainty begins.
A practical sequence is to interpret the rate, calculate one period's interest, find the closing balance, and then use that closing balance for the next period. Only after those steps feel clear do you compare compound interest with simple interest, where interest is calculated on the original principal. Each topic should answer one question rather than introduce several new procedures at once.
There is no universal number of minutes or sentences that makes a topic bite-sized. Use a performance test instead: can you describe the task in one sentence and try it without needing another explanation halfway through? If calculating interest requires you to stop and work out percentages, make that percentage calculation your next topic. Conversely, if finding the interest and updating the balance already feels straightforward, you can combine them into one short task.
Choose Your Starting Point: Calculate One Period of Interest First
Begin with the earliest step you cannot yet complete confidently, not necessarily the first page of an explanation. If percentages are comfortable, start with one year's interest. If they are not, begin by connecting five per cent with five hundredths. You are looking for the smallest missing piece that prevents the next calculation from making sense.
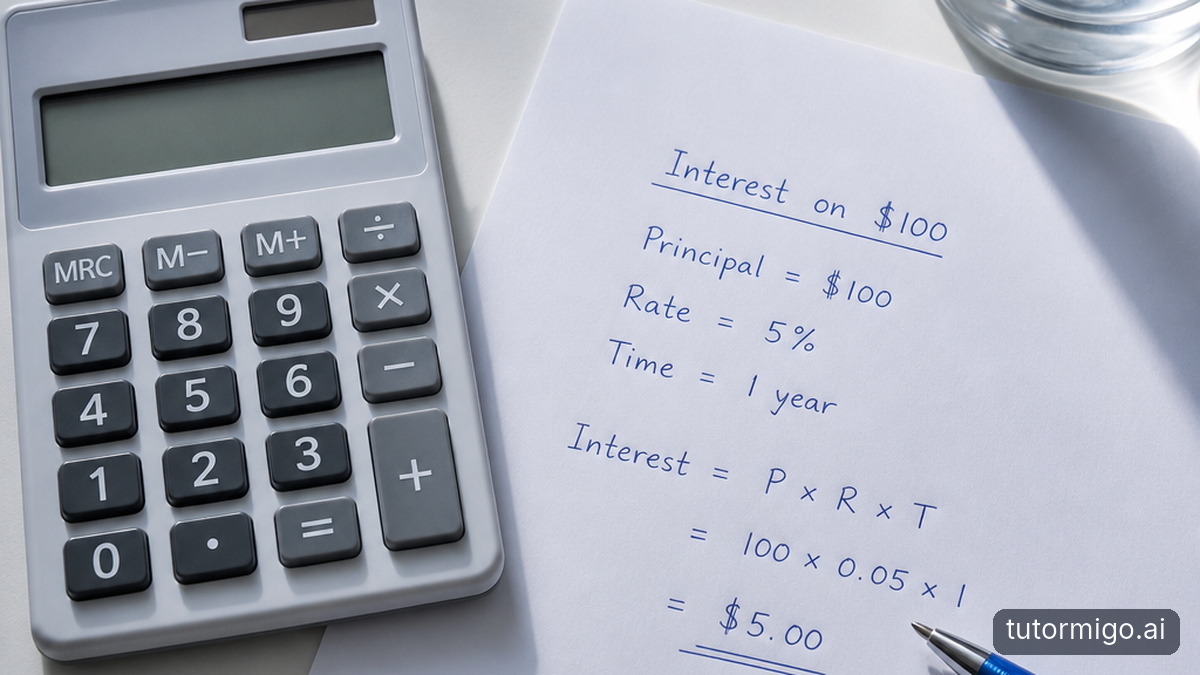
Using the simplified account, calculate the first year's interest: . The account earns $5. Then add that interest to the starting amount: . The closing balance is $105. Keep those two calculations separate initially. One finds the new money earned; the other finds the total now in the account. Mixing up those outputs can make an otherwise correct calculation confusing.
Check the meaning before reaching for a more elaborate formula. Five per cent of $100 should be $5, not $50, and the final balance should include the original money. Try explaining the result aloud: “The account started with $100, earned $5 and finished with $105.” If that sentence matches your calculation, you have a firm starting point. You do not yet need to project ten years of growth.
Practise One Step Before Adding Another: How to Know You’re Ready
After following an example, try a nearby version without looking at the working. Keep the rate and time period unchanged, but start with $200. At an annual rate of , one year's interest is $10 and the closing balance is $210. Changing just one detail helps you check whether you understand the procedure rather than remember the original answer.
You are ready to add the next step when you can complete a fresh example, explain why you used that operation and spot an implausible result. A correct answer alone is less informative if you cannot say what it represents. You do not need flawless speed or a long run of perfect attempts. Look for a repeatable process you can use without copying.
Now return to the original account's second year. The starting balance is $105, so the interest calculation becomes . Adding $5.25 produces a balance of $110.25. The extra interest appears because the previous year's $5 also earns interest. If you accidentally reuse $100, pause at that specific choice. Practice identifying the next period's starting balance before adding more years or changing the compounding frequency.
Track Progress Simply: What You Can Now Explain or Calculate
Track what you can do, not just how much time you have spent. “Spent twenty minutes on compound interest” records effort, but it does not reveal what became clearer. “Calculated one year's interest without copying” gives you evidence of progress and a sensible place to begin next time. A notebook margin or a single note on your phone is enough.
Use three plain labels: “not yet,” “with help” and “on my own.” Apply them to specific actions, such as finding one period's interest, calculating the closing balance and choosing the next period's starting balance. Keep a worked example beside each completed action. If you can calculate $5 of interest on $100 but still need a reminder to add it back, your record should show that distinction.
Add a brief explanation when you can: “The second year earns more because the balance includes earlier interest.” This captures understanding that a check mark alone might miss. When something goes wrong, record the precise sticking point rather than resetting everything to zero. “Used the original principal in year two” tells you what to practice next. Your progress record should make the next decision easier, not become another complicated task.
Start Today With One Topic, One Short Task and One Visible Progress Marker
Choose one topic from the sequence that is not yet secure. If you are starting from scratch, choose calculating one period's interest. If you can already do that, choose updating the balance or identifying the amount used for the next period. Resist selecting the whole subject again under a smaller-sounding label. Your choice should name one action you can attempt now.
Give yourself a short task with a checkable answer. For example, calculate one year's interest on $300 at a fixed annual rate of , then find the closing balance. Work it out before checking: the interest is $15 and the closing balance is $315. If you are practicing only the interest calculation, stop at $15. Completing your chosen task matters more than squeezing in an extra step.
Finally, choose one visible marker: date the example and mark it “on my own” if you completed it without copying. If you needed help, mark that honestly and note the step to retry. Either result gives you a clear next move. You do not need to understand every version of compound interest today. You need one topic you can name, one task you can finish and one piece of evidence showing where you stand.
Frequently asked questions
Small enough to describe as one action with a checkable result. If another unfamiliar procedure interrupts it, separate that procedure into its own topic.
Move on when you can complete a fresh example without copying and explain what the answer means. Speed is not the deciding factor.
Keep one worked example for each action and label it “not yet,” “with help” or “on my own.” Record the specific next step.
Enjoyed this read?
Like, share, or comment below.
Comments
0Sign in required · respectful discussion · replies supported
Loading comments…