
Why practical money skills matter
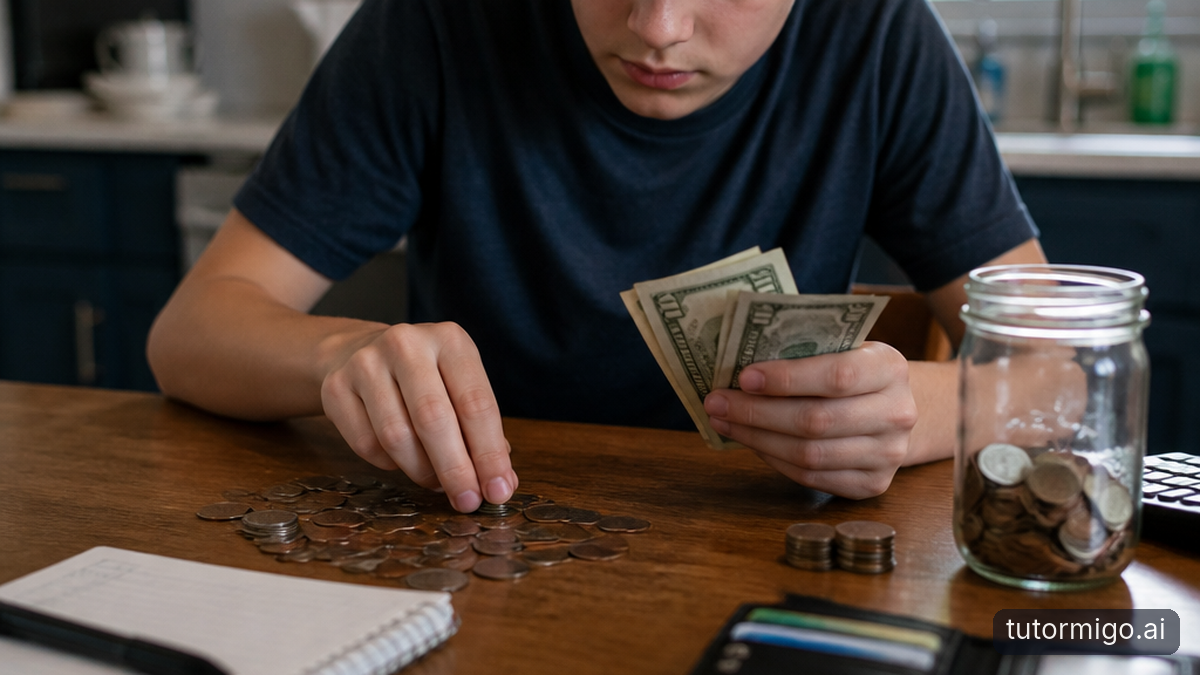
When money decisions feel abstract, it is easy to postpone learning about them until a real choice feels urgent. You may be deciding whether to save for a purchase, compare two prices, or understand why a balance changes. Parents and teachers may want to help, but a lecture about money rarely feels as useful as practising a decision in a realistic situation.
Practical money skills turn everyday moments into manageable learning opportunities. A student can practise separating a need from a want, planning a small purchase, or checking whether a monthly plan leaves room for saving. These skills support independence because they help you explain your reasoning, not simply remember a definition.
For example, imagine receiving $30 for the week. You might assign $15 to planned spending, $10 to a savings goal, and $5 to unexpected costs. The important lesson is not that this exact split always works. It is that you can make a plan, test it against a situation, and adjust it when circumstances change.
Good money learning is less about predicting every future expense and more about building a repeatable way to think through choices.
Learn through guided, connected practice
An AI Tutor can make money topics easier to explore because you can ask for an explanation, try an example, and follow up when a step is unclear. In a TutorMigo.ai tutor workspace, you could ask why saving first changes a spending plan, then request a new scenario with different numbers. The conversation can stay focused on the idea you are practising rather than turning into a general search for information.
Session continuity is useful when a topic takes more than one attempt. You might begin by learning the difference between income, spending, and saving. In a later session, you can return to a similar scenario and explain your choice more clearly. That progression helps you notice whether you understand the reasoning or are only copying a familiar pattern.
Try asking for one decision at a time: “Give me a weekly budget with three spending choices,” or “Let me decide what to change when an unexpected cost appears.” Then explain your answer before asking for feedback. This keeps the activity active and gives you a chance to spot assumptions, such as forgetting a recurring expense or treating all available money as spending money.
TutorMigo.ai benefits are strongest when you use the AI Tutor as a practice partner, not as a substitute for your own judgment. Ask it to show a method, check your reasoning, and offer another example.
Make saving and budgeting visible
Money concepts become more understandable when you can see how a decision affects the rest of a plan. Start with a simple scenario: you have $40 available for a weekend and want to save $12 for a larger goal. That leaves $28 for current choices. If transportation costs $8, you can compare what remains after that cost with what remains if you choose a cheaper option.
You can describe the relationship with a simple formula: savings rate = rac{ ext{savings}}{ ext{income}} imes100\%. For the example, the savings rate is = rac{12}{40} imes100\%=30\%. The point is not to chase a particular percentage. The calculation helps you see how a choice changes the plan and gives you language for discussing it.
Interactive study tools can make this kind of reasoning less passive. Use a whiteboard-style workspace to lay out income, planned spending, savings, and unexpected costs. Move one amount at a time and explain what changes. If you make a mistake, revise the plan and compare the two versions rather than erasing the first attempt immediately.
That process also helps families and teachers ask better questions. Instead of saying “Was that a good choice?” they can ask, “What goal did the choice support?” or “What would change if the cost were higher?” Those questions build flexible thinking without turning a classroom or family conversation into personalized financial advice.
Remember the ideas with spaced review
Budgeting vocabulary can fade quickly when it is introduced once and left alone. Terms such as fixed cost, variable cost, saving, spending, and trade-off are easier to use when you meet them repeatedly in different examples. Spaced-repetition flashcards can support that process by bringing back a concept after a delay, rather than asking you to reread the same explanation in one sitting.
A useful card should make you retrieve an idea. Instead of writing only “What is a trade-off?” create a prompt such as, “You spend more on transportation this week. What might you give up, delay, or change?” Another card could ask you to distinguish a planned cost from an unexpected cost in a short scenario. The answer should explain the reasoning in plain language.
TutorMigo.ai flashcards can help you build a small deck from a lesson and review it on a schedule. Keep the deck focused: perhaps ten cards about planning, saving, and everyday choices rather than a large collection of unrelated definitions. After a review session, mark which cards felt uncertain and use an interactive tool or tutor conversation to work through those ideas.
Parents, teachers, and lifelong learners can also use the cards as conversation starters. Ask the learner to explain an answer with a new example. If the explanation changes when the numbers change, that is useful evidence that the learner is developing understanding instead of memorising a phrase.
Track progress without turning money into a test
Progress in practical money learning is not only a score. It can look like identifying a recurring cost, explaining why a plan needs an adjustment, or comparing two choices without assuming there is one universal answer. A structured learning path can still help you record those milestones and decide what to practise next.
For instance, begin with a goal such as “I can build a simple weekly plan.” Then practise three situations: a normal week, a week with an unexpected cost, and a week with a new savings goal. After each one, note whether you could explain the choices and what confused you. This creates a clearer picture than completing one quiz and moving on.
TutorMigo.ai can support this approach through guided tutoring, practice tools, and progress tracking. A student might revisit a weak concept, review related flashcards, and then try a fresh scenario. A teacher could assign a practical exercise and look for the reasoning behind the response. The focus stays on growth and explanation rather than presenting a financial decision as universally correct.
Structured preparation can also be useful when a learner is working toward a broader study goal that includes planning, data interpretation, or applied problem solving. The same habit applies: set a target, practise in small steps, review performance, and adjust the next activity. That is a transferable learning routine, not a promise about any particular financial outcome.
Keep learners supported and decisions grounded
Learning tools work best when they leave room for real-world context. A general-purpose generative chatbot may produce a quick explanation or example, while a dedicated AI Tutor workspace is designed to support an ongoing learning session with follow-up questions and practice. The practical difference is the learning structure you create around the conversation: goals, review, interactive work, and reflection.
For a student, that might mean asking for a scenario, making a choice independently, and then requesting feedback on the reasoning. For a teacher, it might mean assigning a short activity and checking which concepts need more practice. For a parent, visibility into progress can make it easier to ask supportive questions without taking over the decision.
Use sensible boundaries. Practice examples should not be treated as personal financial advice, and a real decision may depend on local rules, household circumstances, prices, or guidance from a qualified professional. The learning goal is to build questions and habits: What is the goal? What costs are already committed? What alternatives exist? What could change?
Those habits explain the broader TutorMigo benefits. Students gain a place to practise without embarrassment, families can discuss progress with more context, and teachers can connect abstract terms to realistic choices. The result is not a prediction about the future; it is stronger everyday reasoning.
Start with one realistic decision, explain the trade-off, and review the idea again later. Small practice sessions can make money topics feel much less intimidating.
What to do next
Choose one practical topic for your next session: planning a small purchase, setting a savings goal, comparing two options, or handling an unexpected cost. Write down the scenario using simple, fictional amounts. Then ask an AI Tutor to guide you with questions rather than immediately giving you the answer.
After you complete the example, turn two or three important ideas into flashcards. Return to them later and try a different scenario. If you are learning with a parent or teacher, explain one decision aloud and invite them to ask what would change under different conditions. That conversation can reveal where you need more practice.
Keep the goal modest and observable: “I can explain how one change affects my plan.” Once that feels comfortable, add another situation. With repeated practice, practical money skills become less about memorising terms and more about making thoughtful, informed everyday decisions.
Pros and cons
Pros
- Connects money concepts to realistic, low-pressure practice scenarios
- Supports follow-up learning with session continuity and review
- Combines tutoring, interactive tools, flashcards, and progress tracking
Cons and limitations
- Practice examples are educational and not personalized financial advice
- Learners still need to apply context and judgment to real-world decisions
Frequently asked questions
Students can practise distinguishing needs from wants, planning a fictional budget, setting a savings goal, comparing options, identifying trade-offs, and explaining how an unexpected cost changes a plan.
TutorMigo.ai can provide guided AI tutoring, interactive practice, spaced-repetition flashcards, and progress tracking for learning activities. Use fictional examples for practice and do not treat them as personalized financial advice.
No. It is a learning platform for exploring concepts and practising reasoning. Real financial decisions may require context-specific information or guidance from a qualified professional.
They can ask learners to explain their reasoning, compare alternative scenarios, review progress, and discuss what information would matter in a real situation without prescribing a personal financial choice.
Enjoyed this read?
Like, share, or comment below.
Comments
0Sign in required · respectful discussion · replies supported
Loading comments…