
The Personal Finance Lessons School Never Taught You
 You can pass algebra, write an essay, and still feel unprepared when a paycheck arrives, a bill is due, or a credit card offer lands in your inbox. Many people learn money rules only after making expensive mistakes. The things school never taught often include the practical habits that turn income into security: planning, comparing choices, and understanding long-term consequences.
Start with the idea that money is a set of decisions, not just a number in your account. You decide what to spend now, what to reserve for later, and what risks you can afford to take. A person earning more can still feel broke if every increase in income becomes a new expense. Someone with a modest income may create stability by building a small emergency fund and checking recurring charges.
Financial literacy also means asking better questions. Before buying something, ask whether it solves a real need, whether you could pay for it without borrowing, and what you are giving up instead. A $40 weekly habit costs about $2,080 over a year, before any fees or growth. That does not make the purchase automatically wrong; it makes the trade-off visible. Once you can see those trade-offs, everyday money becomes less mysterious and more manageable.
How to Build a Budget You Can Actually Follow
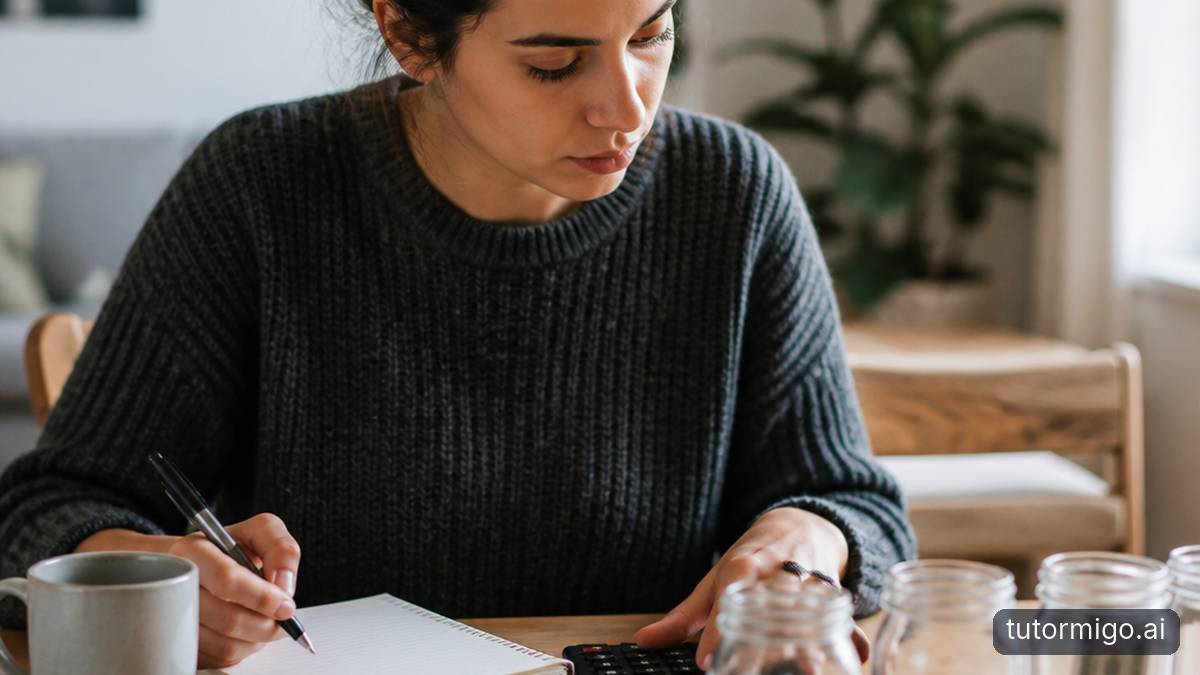 A useful budget is not a punishment or a prediction of perfect behavior. It is a plan that gives every part of your income a job. Begin with take-home pay, then list fixed costs such as rent, transportation, insurance, and minimum debt payments. Add flexible costs, including food, entertainment, clothing, and gifts. Finally, include irregular expenses by estimating their yearly total and dividing it by $12. A $600 annual insurance bill becomes a monthly target of $50.
Next, compare the plan with what really happened over the last month. If groceries were $450 rather than the $300 you guessed, adjust the budget instead of blaming yourself. A realistic plan might use separate categories for essentials, goals, and flexible spending. Automating a transfer to savings on payday can make the goal happen before the money is available to spend.
Make your budget easy to check in under five minutes. If it requires complicated tracking every day, simplify it until you will actually use it.
Leave room for enjoyment and surprises. A budget with no flexibility often collapses after one dinner out or a car repair. Review it weekly, look for patterns rather than isolated mistakes, and change one category at a time. The goal is not perfect restriction; it is a repeatable system that helps your choices match your priorities.
How Compound Interest Makes Saving and Investing Add Up
Compound interest is one of the most important money ideas because your returns can begin earning returns of their own. If you invest an initial amount , earn an annual rate , compound times per year, and leave it invested for years, a simplified model is A=P(1+ rac{r}{n})^{nt}. You do not need to calculate this by hand to understand the lesson: time can matter as much as the amount you start with.Imagine two people each invest $100 per month. One begins at age 22 and stops at 32; the other begins at 32 and continues until 62. Depending on fees and returns, the earlier contributions may have decades longer to grow. This is why starting with a small, consistent amount can be more powerful than waiting for the perfect income or a dramatic one-time deposit.
Compound growth also works against you. An unpaid credit-card balance can accumulate interest, so a purchase becomes more expensive while the balance remains. Check the annual percentage rate, fees, and whether interest is charged on new purchases. For saving, look for low-cost, diversified options appropriate to your goals and risk tolerance rather than chasing a guaranteed quick win.
Think in habits: save automatically, increase contributions when income rises, and avoid withdrawing long-term money for short-term wants. Growth is never guaranteed, but patience, diversification, and regular contributions give your plan a stronger foundation.
How Debt and Inflation Change What Your Money Can Buy
Debt lets you use money before you have earned it, which can be useful for education, a home, or an emergency, but the convenience has a price. Before borrowing, check the total repayment amount, not only the monthly payment. A $300 purchase split into small payments may seem manageable, yet interest, setup charges, or late fees can make the final cost much higher. Compare the annual percentage rate and read what happens if you miss a payment.Prioritize high-interest debt because it grows quickly. You might pay minimums on every account while directing extra money toward the balance with the highest rate. Another approach is the debt snowball, which targets the smallest balance first for a quick psychological win. The best method is the one you can follow consistently without taking on new debt.
Inflation creates a different problem: prices rise, so the same amount buys less. If a basket of groceries costs $100 this year and prices rise by $5, the same basket costs $105. Cash kept for near-term needs should be accessible, but money needed years from now may need a strategy that has a chance to grow faster than inflation. That involves risk, so match the choice to the time horizon.
Before taking on a loan, ask how the payment fits alongside savings, essential bills, and future plans. A low payment is not automatically affordable if it leaves no room for setbacks.
What You Need to Know About Taxes Before You Earn and Spend
Taxes are easier to manage when you understand the difference between gross pay and take-home pay. Gross pay is what you earn before deductions; take-home pay is what reaches your account after items such as income tax, payroll taxes, insurance, or retirement contributions. A job advertised at a yearly salary does not mean that full amount is available for rent and spending, so build your budget around actual pay statements when possible.Keep records for income, major expenses, charitable gifts, and tax documents. If you work as a freelancer, taxes may not be withheld automatically, so setting aside part of each payment can prevent a painful bill later. The exact rules depend on where you live and your situation; when something is unclear, use current guidance from your tax authority or ask a qualified professional rather than relying on a social-media shortcut.
Learn the difference between a deduction and a credit. A deduction generally reduces the income used to calculate tax, while a credit generally reduces the tax owed. Neither is a reason to spend money you would not otherwise spend. Also check the terms of workplace retirement contributions, health benefits, and other deductions before choosing them.
Taxes affect everyday decisions, but they should not dominate every decision. Compare after-tax results, keep an emergency reserve, and save documents in one reliable place. The practical lesson is simple: know what you owe, when it is due, and which records support your claim.
How to Make Better Financial Decisions and Put These Lessons Into Practice
Good financial decisions rarely come from finding one perfect rule. They come from slowing down long enough to compare the full cost, likely benefit, and risk. Before a major purchase, write down the price, recurring costs, maintenance, financing cost, and what goal the money could support instead. For example, a used car priced at $14,000 may be more affordable than a $10,000 car with higher insurance and repair costs, but only after you compare the complete picture.Use a short decision checklist: Is this a need, a priority, or an impulse? Can I pay without missing essentials? What happens if my income drops? Have I compared at least two options? Waiting 24 hours before a nonessential purchase can reveal whether the desire lasts. For larger choices, discuss the assumptions with someone you trust and write down what would make you change course.
Put the lessons into practice with a small monthly routine. Check your account balances, review subscriptions, transfer money toward an emergency fund, make a debt payment above the minimum when possible, and update one goal. Celebrate progress such as avoiding a fee or saving your first $100; confidence grows from visible evidence.
If you want structured help practicing unfamiliar ideas, TutorMigo.ai can be a natural next step: its tutor workspace supports guided questions and session history while you work through financial examples. Use it to clarify concepts, then verify important tax or investment decisions with authoritative sources or qualified professionals.
Frequently asked questions
The most useful missing lessons are budgeting, compound interest, borrowing costs, inflation, taxes, investing basics, and the habit of comparing long-term trade-offs before making a decision.
Start with take-home income, fixed bills, flexible spending, savings goals, debt payments, and irregular expenses. Review actual spending for a month, then adjust the plan to match reality.
Early savings have more time to earn returns and potentially earn returns on those returns. Consistent contributions and time can matter more than waiting until you can make a large deposit.
Review the annual percentage rate, total repayment amount, fees, late-payment rules, and whether the payment still fits after essential bills, savings, and likely emergencies.
Related reading
Related reading
Enjoyed this read?
Like, share, or comment below.
Comments
0Sign in required · respectful discussion · replies supported
Loading comments…